Gateway for Cashless Payments: Examining Young Consumers Preference for Digital Wallets
Fathimath Thasni. V
Assistant Professor, Dept. of Commerce, KTM College of Advanced Studies, Karuvarakundu, Malappuram
Volume No : 6
Issue No : 2
This study investigates young consumer's preferences, adoption, and satisfaction levels regarding digital wallets in the Malappuram district. Using structured questionnaire primary data collected from 80 respondents to evaluating the usage level, key drivers and operational challenges faced by them in the platform of google pay,paytm etc. the empirical findings reveal that young consumers rapidly using digital wallets for their routine financial activities including mobile recharges, ticket booking bill payments and also for peer to peer money transaction the major factors influencing them for the usage is 24/7 availability and ease to use and the demographic factors are independent to the satisfaction level such as age, gender..etc however the operational hurdles like slow connections and processing time and occasional failure stand some obstacles. The research highlights the vital role of digital wallets in fostering a cashless economy among youth. If service providers focus on the obstacles faced by users helps to ensure sustained long-term consumer trust and engagement
Key words: digital wallets, cashless payments, consumer preferences, Paytm, Google Pay, user satisfaction, recharge, transfer.
1. Introduction
In today's world, smartphones have become an important part of everyday life. As they have become more affordable, the number of smartphone users has increased dramatically. According to data released by TRAI (Telecom Regulatory Authority of India), there are around 1.3 billion mobile phone users in India. Nowadays, smartphones serve not only as communication devices but also for entertainment, web browsing, and financial transactions. By hosting mobile apps, they allow users to make payments and store items like receipts, coupons, and bills, effectively replacing physical leather wallets. Technological advances have made smartphones an essential part of people's daily lives.
Digital wallet money is used in various areas of the world of business, such as banks, customers, and companies. Banks have improved their transaction and payment services to meet customers’ needs. Customers are drawn to the shopping facilities provided by digital wallets because of their convenience and speed. For companies, the aim is to provide transaction services and payment options to clients, and the multiple payment-combination facilities offered by companies are linked to digital wallet services.
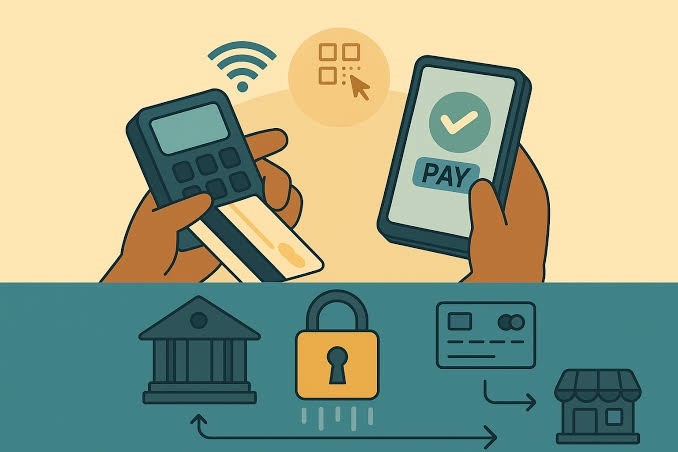
In recent years, the widespread adoption of smartphones has reshaped how individuals manage their day-to-day finances. Physical cash, plastic cards, and paper receipts are now replaced by a single tap on a mobile screen. With the shift to digital wallets, financial technology securely stores all the data related to a particular transaction. Beyond the simple convenience, digital wallets represent a major evolution in global commerce; NFC (near-field communication and QR (Quick Response) encryption protocols offer fast transactions with good security.
2. Review of literature
The literature review evaluated the digital wallets system from early technological adoption to modern lifestyle integration. In this article analyses key drivers of users retention including services, security, demographic differences and post adoption services.
Devan (2015) evaluated awareness levels and mobile wallet services. Findings revealed that rapid growth in smartphone adoption significantly influenced payment habits. The author concluded that consumers are increasingly willing to replace physical wallets with mobile applications for daily transactions, establishing early awareness and basic functional utility as key drivers in the transition toward a cashless mobile ecosystem.
Ghuman and Srivastava (2015) conduct an investigation on A case study on e-payment giants: Free charge & Paytm. he critically questioned whether consumers prefer all-in-one platforms like Paytm or specialized domain platforms like Free charge. The research highlighted key questions surrounding platform versatility versus niche expertise. And he concluded that service bundling and platform convenience strongly shape user preference, forcing digital payment providers to carefully balance broad service integration against domain-specific reliability.
Shukla (2016) outlining digital wallets operational types, advantages, and disadvantages. The paper highlighted that while initial adoption depends on marketing strategies, long-term success requires functional performance. The author concluded that Digital wallets provide good tools for digital businesses to engage customers directly. And he emphasized that regardless of current market saturation, businesses must leverage emerging mobile wallet opportunities to enhance customer engagement and streamline payment workflows.
Mehta (2019) Investigated in the field of customer satisfaction across demographic divides and The empirical findings revealed contrasting demographic priorities: urban consumers prioritized high processing speed, multi-card integration, and loyalty rewards, while rural users valued network reliability, zero fees, and localized interfaces. The study finded that a one-size-fits-all design leads to regional dissatisfaction, arguing that payment providers must tailor features and support mechanisms to distinct socio-economic needs.
Sharma and Gupta (2020) examined the impacts in security protocol and establishing that perceived security risks are the strongest negative of user satisfaction. And he proved that visible security mechanism—such as biometric verification, multi-factor authentication, and real-time alerts—substantially reduced consumer anxiety. The study concluded that incorporating multi-layered protection actively builds customer trust, proving that transaction safety and privacy are essential prerequisites for long-term platform retention.
Yang et al. (2021) analysed in the field of SEM –structural equation modelling. The authors discovered that embedding e-wallets into daily routines—like food delivery, and utility payments—mediates sustained satisfaction. Users integrating e-wallets into daily schedules displayed significantly higher engagements. The study concluded that payment gateways achieve maximum satisfaction when they evolve beyond simple peer-to-peer money transfers into comprehensive lifestyle hubs that simplify everyday routines.
Muhtasim et al. (2022) investigated in the field of service quality of digital wallets .and he find that while promotional discounts attract short-term sign-ups, long-term loyalty relies on backend data privacy, fraud protection, and responsive customer support. The authors emphasized that when payment disputes occur, fast and empathetic customer support determines whether users stay. Ultimately, post-adoption satisfaction depends far more on operational trust and dispute resolution than on initial marketing incentives.
Dev, Gupta, and Kumar (2024) investigated about the Impact of Unified Payments Interface and the customer satisfaction and he reported an exceptionally high approval rate exceeding 91% among respondents. Primary
satisfaction drivers included instant settlement times, zero transaction fees on personal transfers, and seamless QR-code interoperability across platforms. The study confirmed that eliminating cross platform barriers drastically improves convenience, establishing instant execution, zero cost, and universal acceptance as modern benchmarks for satisfaction.
3.Objective of the study
3.1 To study the consumer preference towards usage of digital wallets for cash less payments.
3.2 To identify the factors attracting by consumers to the usage of digital wallets.
3.3 To understand the problems faced by consumers while using digital wallets.
3.4 To study the level of satisfaction of consumer in using digital wallets.
4. Research methodology
Descriptive research design is used for this study. Descriptive research design is a type of research design that aims to obtain information to systematically describe a phenomenon, situation, or population. More specifically, it helps answer the what, when, where, and how questions regarding the research problem, rather than the why.
4.1 Source of data
The study is based on both primary and secondary data.
4.2 Primary data: The primary data which is obtained from the Digital wallets users of Malappuram district it was obtained through detailed survey using a structured questionnaire through google form.
4.3 Secondary data: The secondary data which is used for the purpose of analysis. The secondary data are collected from review of literature, journal, published books and websites.
4.4 Area of the study: area of the study limited to Malappuram district.
4.5 Sampling technique: the study employed convenience sampling. By considering the accessibility and willingness of the respondents participated in the study.
4.6 Sample size: study consist of 80 respondents representing the digital wallets users in Malappuram districts.
4.7 Tools for data collection and presentation
The data required for the study were collected from the selected samples using structured questionnaire. The various tools used for presentations are ,
Bar diagram
Tables
4.8 Tools used for Data analysis
Percentage
Anova
T test
Chi square
Ranking
5.Results and Discussion
Demographic profile of respondents: the demographic analysis indicates that 59% of respondents are male and 41 % are female. And majority of the respondents belonging to 20-28 age group indicating that majority of the digital wallets users are youth. Regarding educational qualification, 60% were graduates, while 40% non-graduates reflecting a highly educated sample with good digital literacy.
Awareness and adoption of digital wallets: majority of the respondents 75% are highly aware about the different features of digital wallets.
6.Findings
The study reveals that respondents are highly aware of digital wallets, with 82% using them regularly for transactions, and the majority are satisfied with the facilities offered by digital wallets. paytm leads as the most preferred platform at 35% and google pay closely followed by 33.75% while other wallets preferred by 2.5%.the major reason for using mobile wallets is its ease to use, 24/7 availability, brand loyalty and shopping convenience. The respondent mainly prefers digital wallets for shopping (21.5%), bill payments (21.5%)and 22% use for money transferring,19.3% use the for transportation and 10% using for movie ticket booking.
The demographic factors like income, age, gender and the occupation show no significant influence on preference, usage pattern or overall satisfaction level. Internet serve as the primary source of information, alongside friends, newspapers, journals, TV, and word of mouth. Despite minor technical obstacles like slow connectivity and delayed transactions, as well as ongoing challenging around fund security, mobile wallets are well positioned to transform traditional modes of online payment in the future.
7. Suggestions
To promote the wide spread usage of digital wallets, provide security to the consumers while using Digital wallets. For the adoption of the digital wallets the providers prioritize the improvements in core operational facilities and user support mechanism. The study recommends that to provide the Digital wallets to give the possible information to the consumers. The study reveals the give more privacy to the consumers for the use of Digital wallets it will enhance the satisfaction and usage level. And the awareness of the digital wallet providers is rising when compared to the preference of usage of services. Also give more fast to the services of Digital wallets for increasing the number of customers. There is a recommendation to give more usage videos to the consumers to increase their usage of Digital wallets.by combining the data protection and minimizing the hurdles helps to get more satisfied customers. 8.Conclusion
This study examined the young consumer’s preference of Digital wallets gate way for cashless payment in Malappuram district. It also aims to find out the consumers preference towards usage of Digital wallets for cashless payment, consumers level of satisfaction in using Digital wallets, to understand problem faced by the consumers in using Digital wallets.
Digital wallets will play a significant role in day to day life as an increase in use of smart phone can be seen and people are relying on digital life style to make things convenient and fast. The respondents get information about the Digital wallets is internet. The most of the people use Digital wallets is Paytm. Most preferable usage of Digital wallets is recharge and utility of bill payment. The study implies the today life is more important to the Digital wallets services. Digital wallets has become extremely convenient for a person to make cashless transaction. After the demonetization the usage of Digital wallets is increasing day by day. So, the Digital wallets service method is help to people for bill payment,
9.Limitation of The Study
9.1 The study relies on a sample size of only 80 respondents which restrict the generalizing ability of the findings.
9.2 Data collection confined to the Malappuram districts so the applicability to another region is limiting.
9.3 Certain participants are showed reluctance in answering specific question so it affects accuracy of the study. 10.Scope for Future Research
10.1 Future research can expand the area of the study like including multiple districts major metropolitan centers and different region helps to improve the accuracy of the study.
10.2 Researcher can increase the sample size from 80 to avoid sample bias and it helps to increase validity of the findings.
10.3 Futures studies can evaluate the adoption barriers security concern and digital literacy among old group etc.
10.4 Also address the technical and security challenges of users to understand the obstacles to improving the functioning of digital wallets. 11. Reference
11.1 Dev A Gupta and Kumar S (2024) Impact of unified payment interface(UPI) on customer satisfaction in modern digital transaction . journal of electronic commerce research ,25(1) 45-58
11.2 Muhtasim D A, Tan S, Hassan M (2022) Service quality and dispute resolution as key drivers of post adoption digital wallet loyalty. Journal of retailing and consumer services ,68,103025
11.3 Yang x, Zhang L,Liu Y (2021) Ecosystem integration and daily routine embedding in e-wallets satisfaction A structural equation modelling approach information and management 58(6)103498
11.4 Sharma R , Gupta M (2020) The impact of security protocols and perceived risk on user satisfaction in mobile payments application . computers in human behaviour, 108,106312
11.5 Mehta P (2019) analysing customer satisfaction across demographic divides in digital payment system . international journal of human computer interactions 35(12)
11.6 Shukla S (2016) digital wallets operational types ,business advantages and implementation challenges .journal of internet banking and commerce,21(2) 1-14
11.7 Ghuman K and Srivastava CS (2015) a case study on e- payments giants freecharge and paytm ‘recharging’ IOSR journal of business and management 15(1)87-92
11.8 Devan A(2015) awareness level and adoption of mobile wallets services : a study on consumer payments habits .international of bank marketing 33(4)412-428